
Income Protection insurance is one of the most crucial and flexible insurance covers available and we can arrange quotes and comparisons for you. It is designed to replace your income if you are unable to work due to sickness or injury, covering you 24 hours a day, worldwide. Your health and happiness, your ability to earn an income is without doubt your most valuable asset and this must be protected. Providing for yourself or your family is your biggest responsibility. We can help provide quotes and policy comparisons across several insurers.
Why is Income Protection Insurance important?
Your most valuable asset can be your ability to produce an income and this must be protected. Unfortunately, nobody knows when an accident or illness may strike. It is a little known fact that most insurance claims are for illnesses and these are not covered by Workers’ Compensation or other social security payments. People insure their cars, home and contents, yet maintaining all of these material possessions is reliant on our ongoing ability to earn an income. If you are sick or injured you may have some sick leave, or are able to draw on cash reserves for a short period of time. But consider the financial consequences of longer term incapacitation of 3 months or longer.
How long could you survive financially if your income stopped tomorrow?
Implementing an insurance policy which provides a monthly income during periods of longer term incapacity represents a logical, cost effective alternative. It is not uncommon for a couple to spend 15 years building up their assets, to then see it all disappear within 2 years because no income was received due to an injury or illness.
How does Income Protection insurance work?
Income Protection insurance is designed to substitute the insured person’s normal income (commonly up to 75% of their normal income for policies first issued prior to October 2021 and 60-70% of income for new policies thereafter) with monthly payments if you are unable to work as a result of illness or injury. The cover can be structured in a number of ways and the following options impact quite considerably on the premium cost:
- Waiting Period (or Excess Period) – The number of days you will need to wait from disablement before monthly replacement benefits become payable. Variables are 14, 30, 60 and 90 days or 6, 12 and 24 months, depending on your possible sick leave or maybe long service leave.
- Benefit Period – The maximum period of time a claim will be paid. Choices are normally 2 years, 5 years or through to age 65 or age 70.
- Claims Escalation (optional) – If a claim occurs, this will index the payments each year in line with the Consumer Price Index or a set percentage. Usually more applicable to Benefit Periods through to age 65.
Agreed Value or Indemnity Value Income Protection Insurance
Agreed Value policies were available to be purchased up until 31 March 2020 but are now generally closed to new applicants. Existing insured policyholders with such cover can apply for increases.
Indemnity Insurance policies are now the standard for new policies and there are sub-types of Indemnity Insurance policies in terms of feature generosity.
The monthly benefit in an Agreed Value policy is derived from your gross income at the time the cover commences. Therefore, under an Agreed Value policy any drop in income will not affect your Income Protection sum insured amount because it was ‘Agreed’ upon when you first took it out. The monthly benefit in an Indemnity policy is derived from your gross income at the time of claim (i.e. it is restricted to the sum insured or 75% [60-70% for policies issued after October 2021] of your income at the time of claim, whichever is the lesser). The benefit with this type of cover is that you sometimes do not have to supply financial records when taking out a policy. The down-side is that you will have to supply this when (if) you come to claim. These policies are generally cheaper than the Agreed Value policies and any drop in income will allow the insurer to reduce the benefits you will receive at claim time. A limited and broad comparison is shown below :
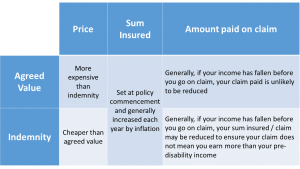
Note that each policy has specific features as described in its Product Disclosure Statement (PDS) and the above is a generalised indication only.
Is Income Protection Insurance Tax Deductible?
Importantly, the cost of Income Protection is largely tax deductible. The cost varies significantly based upon the waiting period, benefit period, amount of income insured and the insured occupation. Unlike some other forms of insurance, there are substantial differences between the quality of Income Protection policies currently available in the market. It is important that you obtain cover which is none restrictive and provide you with the surety and comfort that a legitimate claim will be honoured. The way in which the various policy features and benefits of an Income Protection policy are defined can play a critical role in determining whether a claim is payable – we subscribe to an external research tool (Xplan Risk Researcher), which researches and compares the various contracts available to consumers. We utilise their evaluation to assist in selecting an appropriate policy for you. Please speak with an Experien Insurance Adviser for further information.
Want to read some testimonials from our clients about Income Protection Insurance claims ?
Several case studies are shown below from clients we have helped covering trauma and income protection insurance claims in Australia. The cases highlight successful claims facilitated by Experien’s advisory services, emphasizing rapid payouts, expert support, and financial relief for medical and injury-related events. Our services consistently deliver rapid, stress-free claim processes, often within days, by handling documentation and insurer negotiations. Policies, often set up years in advance, prove critical for professionals (e.g., dentists, doctors) and others facing unexpected medical or injury events. We help manage emotional and logistical burdens (e.g. complex forms) through adviser expertise, allowing clients to focus on recovery or care. Income protection offers ongoing monthly support, crucial for high-risk professions or prolonged recovery. We are proud of the positive client feedback which underscores our efficiency and empathy. Click on the links below to find out more.

The testimonials cover a dentist with heart disease requiring bypass surgery and a surgeon in NSW with a severe medical condition who secured dual trauma and income protection payouts, ensuring financial stability during recovery through adviser-streamlined processes. An IT professional aged 41 received a trauma payout within seven days for a he art attack, leveraging a policy set up 15 years prior, while a retiree with early-stage breast cancer benefited from a policy switch to Clearview, with funds approved in three days. A 59-year-old woman’s stroke claim, handled remotely for her spouse, allowed focus on care with imminent funds. Income protection claims in Victoria include a chiropractor, an anaesthetist, a general practitioner, and a doctor in Melbourne, with varied conditions and successful payouts for income continuity. A cancer patient, a dentist in NSW with an eye injury, a doctor with a fractured wrist, and an individual injured in a bike accident also received income protection payments, supported by Experien’s efficient claim handling. Across all cases, advisers minimized client stress by managing documentation and insurer negotiations, delivering rapid payouts—often within days—and highlighting the value of proactive policy planning for financial relief during medical or injury-related work absences.
- Income Protection Insurance Claim In Victoria in 2024. A 43-year-old woman in Victoria was diagnosed with bowel cancer and underwent emergency surgery. Experien Insurance Services provided compassionate support throughout her recovery and managed her income protection insurance claim, achieving a successful outcome. Click here to read our client’s testimonial.
- A chiropractor suffered a serious side effect from an injection, leading to a six-month work absence. With the help of Experien Insurance Services, the chiropractor successfully claimed income protection and business expense benefits. Read the claim testimonial
- A client diagnosed with cancer expressed gratitude for the professional support provided by Experien Insurance Services in successfully managing their income protection insurance claim. The full testimonial can be seen here.
- A dentist who had considered cancelling their income protection policy was thankful they kept it. After a medical incident, the policy provided financial support, allowing them to maintain their lifestyle. The claim was managed professionally by Experien Insurance Services. Read the full testimonial here
- An anaesthetist faced challenges claiming income protection after a life-saving surgery. Our adviser stepped in, offering dedicated support and successfully managing the claim. Read the testimonial here.
- A Doctor praised us for his exceptional support following a mountain bike accident. We managed the income protection claim, reducing stress and ensuring financial stability during recovery. See the details here.
- A dentist in NSW faced health issues over three years. Experien Insurance Services provided consistent support, making the income protection claim process smooth and respectful. You can fund this testimonial here.
- A GP who delayed getting income protection was thankful for our guidance. After an injury, we helped manage the claim, allowing the GP to focus on rehabilitation without financial stress. Read the full testimonial.
- A client shared a heartfelt testimonial about our support during her husband’s diagnosis with a rare genetic condition. The income protection insurance provided financial stability during a difficult time. Read the testimonial here.
- A dentist in Victoria broke her arm during a run and was unable to work for six weeks. Experien Insurance Services efficiently managed her income protection claim, ensuring timely financial support. Read the testimonial here.
- A dentist suffered a neck injury in a sporting accident. We managed the income protection claim, allowing the dentist to focus on recovery without financial concerns. The details of this claim and the testimonial can be read here.
- Following a mountain bike accident, a client praised us for our advocacy and support in managing the income protection claim, ensuring financial stability during recovery. You can access the full testimonial here.
- A dentist who retained their income protection policy on our advice was able to claim successfully after a career-ending eye injury. We guided them through the process, providing financial peace of mind. You can access the details of the client’s testimonial here.
- A doctor who fractured his wrist received support from Experien Insurance Services. The claim was managed professionally, ensuring financial assistance during recovery. The details of the testimonial can be seen here.
- An emergency specialist doctor in Melbourne praised us for simplifying the income protection claim process during a period of prolonged sick leave. Read the full testimonial here.
- A client expressed deep gratitude for our support during a challenging time, emphasizing the importance of having income protection insurance and a dedicated broker. Read the details here
Want to read more about Income Protection Insurance ?
Click on the articles below to find out more :
Questions And Answers On Income Protection Insurance And Articles On Income Protection Insurance
- Income Protection Insurance claims constitute over 60% of the total number of claims that Experien Insurance Services has helped clients with. Read more on this interesting topic by access the full article here.
- Mental health conditions, including PTSD and depression, are the leading reasons for income protection claims, accounting for 19% of all claims. Of these, 68% are from income protection insurance, 28% from TPD cover, and 4% from life insurance. Read the full details here.
- Want to see Income Protection Insurance claims information across a range of demographics ? Access this information here.
- Insurance products we arrange can provide claim payments for cancer diagnoses. A UK survey highlighted the financial impact of cancer, with many patients reducing work hours or stopping work entirely. Experien offers income protection, trauma, and TPD insurance to mitigate these financial burdens. Read more on this topic here.
- Top causes of income protection claims include accidents, musculoskeletal issues, mental disorders, and cancer. Trauma insurance pays lump sums for specific medical conditions and is not dependent on work status. Read further here on Income protection insurance causes of claim
- Older statistics from one life insurer in 2019 showed the following causes for income protection claims: Accidents (16%), Musculoskeletal (8%), Mental Health (8%), Cancer (6%), Cardiovascular (2%), and Other conditions (60%). You can read the full article here
- A major life insurer’s research has shown the financial burden of serious illnesses like cancer. One in three men and one in four women will be diagnosed with cancer before age 75. Out-of-pocket costs can be substantial, with some drugs costing over $5,000/month. The average lifetime cost of cancer for individuals aged 15-64 is $126,280. Read about this interesting study here
Articles on Income Protection Insurance Covers
- This article discusses the widespread underinsurance in Australia, with 1 million underinsured for death/TPD and 3.4 million for income protection. It emphasizes the importance of reviewing and tailoring insurance coverage to individual needs and circumstances. Underinsurance for Life Insurance, TPD Insurance and Income Protection Insurance
- This article outlines key features of income protection insurance, including waiting periods, benefit periods, and partial disability benefits. It highlights the importance of understanding policy terms and seeking financial advice to choose suitable coverage. Income Protection Insurance Features
- This article explains the ‘Guaranteed Renewability’ feature in life insurance policies, ensuring continued coverage as long as premiums are paid. It reassures policyholders that insurers cannot cancel or alter coverage due to changes in health status after policy issuance. Can a life insurer ever cancel or change your income protection or life insurance cover ?
- This article describes the ‘Offset Clause’ in income protection policies, which adjusts claim payments based on other income sources during disability. It aims to prevent overcompensation and encourages return to work, with variations across insurers. What Is An Income Protection Insurance Offset ?
- This article compares workers’ compensation and income protection insurance, highlighting that most injuries occur outside the workplace and are not covered by workers’ compensation. It advocates for income protection as a more comprehensive financial safeguard. Workers Compensation Insurance versus Income Protection Insurance
- This article focuses on tailored income protection policies for doctors and dentists, addressing their unique occupational risks. It emphasizes the importance of choosing suitable waiting and benefit periods and the role of brokers in managing claims. Income protection insurance for medical professionals
- This article explains why income protection is crucial for doctors, especially those without extensive sick leave or financial reserves. It discusses policy customization options and the role of brokers in providing advice and claims support. Why do Doctors need Income Protection Insurance
Articles on Income Protection Insurance Costs
- This article provides guidance on comparing income protection quotes, detailing factors that influence pricing such as age, health, occupation, and policy features. It encourages consulting brokers like Experien Insurance Services for personal advice. Compare Income Protection Quotes
- The article offers options to lower income protection insurance costs, including adjusting coverage amounts, waiting periods, and benefit periods. It recommends reviewing policies with brokers/advisers to find cost-effective options. Reducing Income Protection Insurance Premium Costs
- This article examines how waiting periods and benefit payment periods affect the cost of income protection insurance. It provides examples to illustrate the impact of these variables on premiums. Income protection insurance quotation options
- The article discusses the benefit payment period in income protection policies, which determines how long claims can be paid. It explains options ranging from 2 years to age 65 or beyond. Income Protection Insurance Quotes – How long can a claim be paid for ?
Other Articles on Income Protection Insurance
- This article likely addresses considerations for obtaining income protection insurance with high blood pressure, including underwriting processes and potential premium loadings. Income Protection Insurance And High Blood Pressure
- This article likely discusses the challenges and considerations when applying for disability insurance with a history of lower back pain, including medical assessments and policy exclusions. Applying for disability insurance with lower back pain
Important Information About The Details On This Page
The information provided contains general information and examples and does not take into account your personal objectives, financial situation or needs. It is important, before deciding whether to act on any of the topics. that you consult a licensed or authorised financial adviser if you require financial advice that takes into account your personal circumstances. You should also review the Product Disclosure Statement (PDS) issued by each insurer before considering further. Note that the policy wording will differ from insurer to insure and loadings, exclusions and other limitations may apply by the insurer to each applicant on a case by case basis.

