Definition of Professional Dental Indemnity Insurance
A Professional Indemnity Insurance arrangement for a Dental Practitioner, as per the Dental Board Of Australia, is an arrangement – that secures for the practitioner – insurance against civil liability incurred by, or loss arising from, a claim that is made as a result of a negligent act, error or omission in the conduct of the practitioner. This type of insurance covers the costs and expenses of defending a legal claim, as well as any damages payable. The full standard (as at March 2026) can be found here. Experien General Insurance Services (Experien) helps Dental Practitioners to arrange such insurance cover.

A comprehensive package to protect you and your practice
- The security of a large Global professional indemnity insurer.
- Your own insurance manager for you to access at any time.
- No call centres.
- High standard coverage of $20m for claims and potentially more with defence costs paid in addition to the policy limit.
- Pricing is not dependent on membership of the ADA.
- A national team with consistent pricing and services in each state
- Legal representation and defence support with extensive claims experience.
- Peer support (separately to the insurance policy) by experienced dentists currently working in commercial private practice.
- Risk management resources and services.
- The availability of public liability cover in addition to professional indemnity insurance cover
- Used by hundreds of dentists around Australia with thousands of claims, notifications and support services provided to date.
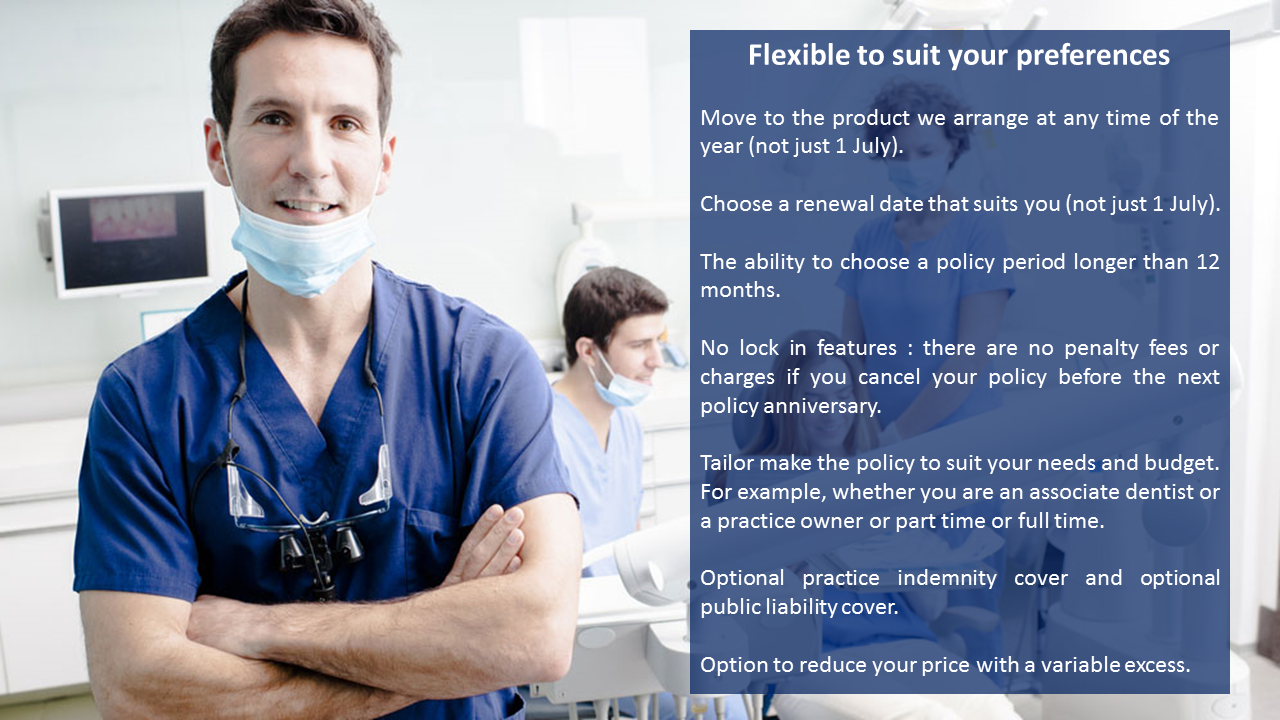
- Product flexibility
- Flexible excess options to reduce costs
- The ability to add Practice Indemnity Cover without needing a second policy
What type of dental practitioners can Experien assist?
- Private practice dentist – self employed or contractor/associate
- Solo employee, contractor or locum dentist wanting a highly portable policy
- Practice owners who also want cover for their practice legal entity
- Dentists who want public liability cover in addition to their professional indemnity insurance cover
- Specialist Dentists such as Orthodontists and Prosthodontists
- Practice employed dentists
- Part time private practice dentist – less than 20 hours pw
- Oral and maxillofacial surgeon – arrange via a medical indemnity insurer
- Retired dentists – conditions apply
- Oral health therapist
- Dental hygienist
- Dental technician
- Dentists performing cosmetic facial aesthetics – conditions apply
- General dentists performing implants and/or orthodontics : where you have flexibility to choose one of two options to suit your budget
- Graduate dentists
- 1st Year – employee or contractor
- 2nd Year – employee or contractor
- 3rd Year – contractor only (not self employed)

Experien Insurance Services will provide you with the Product Disclosure Statement/Policy wording issued by the insurer and your own policy schedule for the actual policy wordings applicable to you. Please note that sub limits apply to some coverage as noted in the policy wordings. Experien Insurance Services works with only one insurer for professional indemnity insurance arranged for Dentists. The above is a summary prepared in March 2026.
Experien Insurance Services is not an insurer. For policies renewing from 1 May 2026 and new policies arranged from 1 May 2026, the insurance is arranged via Tego (ABN: 34 608 505 960 and AFSL: 482467) and insured with certain underwriters at Lloyd’s. Experien Insurance Services does not act as an agent of Tego or Lloyd’s.
Historically, AAI Limited ABN 48 005 297 807 trading as Vero Insurance was the insurer for policies arranged by us and renewing up to 1 May 2019. Insurance Australia Limited ABN 11 000 016 722 AFSL 227681 trading as CGU Insurance was the insurer for policies arranged from 1 May 2019 to 30 April 2026. With effect from 1 October 2025, references in any documents to Insurance Australia Limited ABN 11 000 016 722 AFSL 227681 trading as CGU Insurance should be changed to CGU Australia Pty Ltd (CGUA) ABN 62 004 478 960 AFSL 700014 trading as CGU Insurance. In effecting the dental professional indemnity insurance contract with Vero or CGU, Experien General Insurance Services were acting under an authority given to it by the Insurer and Experien General Insurance Services effected the contract as agent of the Insurer and not the Insured
Supporting you
What influences the price of dental professional indemnity insurance ?
Each insurer will set prices based on their own criteria, which can change over time. Common factors taken into account in setting premiums include :
The number of hours worked each week (e.g. full time vs part time work).
The nature of the work done by each dentist (some insurers regard certain procedures as higher risk than others).
The number and amount of past insurance claims of the dentist.
Whether the dentist has faced any issues with Regulators in the past.
Some insurers may differentiate their price based on the location of the dentist (e.g. their state).
There are many other factors that are taken into account. For example, some insurers may charge more if you are not a paid member of an association they are aligned with.
How much does professional indemnity insurance cost for dentists ?
There is a wide range in premiums offered from one insurer to another based on the specifics of each dentist. Prices as low as a few hundred dollars per annum for new graduates to over $10,000 per annum for dentists that are regarded by an insurer as high risk. Many full time dentists in private practice pay premiums between $2,500 and $5,000 per annum.
Am I guaranteed to be able to buy or renew dental professional indemnity insurance ?
No. Insurers generally offer policies for a one year duration. At the end of the policy year, the insurer has the option of offering to renew the policy and can vary the pricing, features or not offer renewal terms at all. The concept of ‘insurer of last resort’ offered to doctors does not exist for dentists.
Are the features across all dental professional indemnity insurance policies the same ?
No. Insurers offer different sub limits and features for coverage as set out in their policy wordings and policy schedules. One insurer may offer cover for Regulatory Claims defence costs of $500,000 whereas another may only offer a limit of $100,000. And, one insurer may offer a limit for Civil Claims defence costs of $10m per claim whereas another may offer a choice of $10m or $20m.
Do dental professional indemnity insurance policies work on a “claims made” basis ?
The Product Disclosure Statement, or Policy Wording, issued by the insurer together with your own Policy Schedule will note the terms that will apply to your cover. Generally, most professional indemnity insurance policies for Dentists work on what is commonly referred to as a “claims made” or “claims notified” basis. This means that, subject to the other terms and conditions, you will be covered for claims first made against you and notified to the insurer during (and not after) the period of insurance. The policies do not generally cover matters you were aware of prior to the commencement of the period of insurance with the insurer. If you notify the Insurer of a matter for which you seek indemnity – after your Policy has expired or is cancelled – you may not be indemnified by the Insurer for that matter. Any public liability insurance component of the policy may not work on a “claims made” basis and may work on an “occurance” basis. This will be noted in your policy wording issued by the insurer.
Two features that are commonly found with “claims made” policies are “Retroactive Cover” and “Run off cover” which are explained below :
What is run off cover ?
Run-off cover is a form of cover generally taken out by Dentists when they retire or in the event they stop practicing permanently. Run-off cover is provided through an extended reporting period which allows you to notify claims against you – or potential claims against you – to the Insurer after the expiry of the period of insurance, in effect extending the period of insurance. You should notify the Insurer when you are going to retire or cease practice so that you can purchase Run Off Cover. If offered, the insurer may do so via an endorsement to your current Policy – giving you an extended reporting period (potentially up to 84 months). Note that Run Off Cover will require an additional premium to be paid for it to be obtained.
What is Retroactive Cover ?
Subject to the Policy Wording and your own Policy Schedule, most insurers will offer what is referred to as “Retroactive Cover”. This means that, as long as a matter that you have cover for, was first made against you (or first came to your knowledge) during the period of insurance with that Insurer, Retroactive Cover broadly means that the insurer will cover you. The cover will be according to the terms of the Policy, even if the incident giving rise to the claim against you occurred before the commencement of the period of insurance with that Insurer, provided it occurred after the retroactive date. The matter must also be notified before the end of the current policy period. The Retroactive Date of your Dental Indemnity Policy determines how much of your prior practice is covered under your Policy.
Subject to the Policy Wording and your own Policy Schedule, most insurers will offer what is referred to as “Retroactive Cover”. This means that, as long as a matter that you have cover for, was first made against you (or first came to your knowledge) during the period of insurance with that Insurer, Retroactive Cover broadly means that the insurer will cover you. The cover will be according to the terms
Want to read more ? Click links below to read more articles about Professional Indemnity Insurance For Dentists
Articles on cover
- This article emphasizes the importance of maintaining current and compliant professional indemnity insurance (PII) for dental practitioners. It outlines the requirements set by the Dental Board and AHPRA, including the need to declare PII during registration renewal. It advises practitioners to verify their coverage, especially when changes in personal or financial details occur, and to cease practice immediately if coverage lapses. Dentists Professional Indemnity Insurance – Make sure you are covered
- This article defines professional indemnity insurance for dental practitioners and describes the comprehensive coverage arranged by Experien General Insurance Services. It includes legal defense, peer support, and risk management services. The article also outlines the types of dental professionals eligible for coverage and highlights the flexibility and support provided by the product. Dental Practitioner Professional Indemnity Insurance
- This article explains the concept of sub-limits in professional indemnity insurance policies for doctors and dentists. It clarifies that sub-limits cap the insurer’s payout for specific types of claims and vary between insurers. The article stresses the importance of understanding these limits as they can significantly affect coverage. Understanding sub limits for doctors’ professional indemnity insurance policies and dentists’ professional indemnity insurance policies
- This article discusses key considerations for doctors and dentists regarding professional indemnity insurance, including coverage for advertising compliance and regulatory investigations. It highlights the importance of understanding policy terms and the revised advertising guidelines by AHPRA and the National Boards. Professional indemnity insurance considerations for doctors and dentists
- This article reviews data from a past Dental Board of Australia’s annual report, highlighting the number of notifications and disciplinary actions against dental practitioners. It underscores the importance of professional indemnity insurance in light of these statistics and regulatory requirements. Dentists in Australia and Professional Indemnity Insurance Considerations
- This article differentiates between public liability and professional indemnity insurance. Public liability covers incidents like slips and falls on premises, while professional indemnity covers clinical errors. It advises practitioners to ensure they have both types of coverage as needed. Difference between Public Liability and Professional Indemnity Insurance For Dentists and Doctors
- What to know more about retroactive cover for dental professional indemnity insurance ? Click here to learn more
- This article outlines the role of professional indemnity insurance in protecting doctors and dentists from claims arising from complaints and feedback. It emphasizes the importance of having appropriate coverage and provides a checklist from AHPRA to help practitioners manage complaints effectively. Professional Indemnity Insurance For Doctors and Dentists
Articles for Dental Practice Owners
- Many practice owners do not consider a potentially important additional type of professional indemnity insurance which will separately protect their business or practice legal entity if a negligence claim is brought against that legal entity instead of, or in conjunction with a claim brought against an individual practitioner. Read more in this article : Dentist Practice Owners Should Consider Practice Or Entity Professional Indemnity Insurance
- This is an article on a topic that is relevant to professional indemnity insurance for practices owned by Dentists that employ other staff. Dental Practice Owners And Vicarious Liability Risks
Dentists and facial injectables
- Article on dentists performing cosmetic facial injectables (Botox) and professional indemnity insurance. Click here to read the details
Dental Professional Indemnity Insurance Claims Articles
- This article presents malpractice claims data from the USA, highlighting common procedures involved in dental professional indemnity insurance claims such as root canals and implants. It emphasizes the importance of understanding global trends and the cost implications of defending such claims. Dental Malpractice Insurance Claims
- The article stresses the importance of timely notification of potential claims under ‘Claims Made’ insurance policies. It discusses a legal case illustrating the consequences of delayed notifications and the insurer’s rights under the Insurance Contracts Act. Early notification of potential claims with professional indemnity insurance for doctors and dentists
- This article highlights the critical role of accurate and timely clinical records in defending professional indemnity claims. It outlines best practices for record keeping as per the Dental Board of Australia’s Code of Conduct. Professional indemnity insurance claims defence for doctors and dentists
- The article outlines the Dental Board of Australia’s guidelines on infection control, emphasizing the need for dental practitioners to maintain hygiene, follow protocols, and ensure public safety. It also discusses the importance of training and compliance. Dentists – complying with infection control obligations
- This article advises dentists to stay informed about Dental Board updates, such as guidelines on teeth whitening products, to ensure compliance and avoid potential indemnity claims. Read more here
- AHPRA has released videos and resources to help practitioners understand the notification process. The article encourages practitioners to engage with these materials to better navigate regulatory concerns. Professional indemnity insurance for doctors and dentists – AHPRA notifications
- The article explains mandatory notification requirements for health practitioners under AHPRA regulations. It highlights recent changes aimed at encouraging practitioners to seek help without fear of mandatory reporting. Dentist professional indemnity insurance news update – mandatory notifications
- This guide helps practitioners understand their professional responsibilities when using social media. It emphasizes maintaining ethical standards and avoiding common pitfalls in online interactions. Guide for doctors and dentists on social media obligations
- The article discusses upcoming forums and resources to help dental practitioners understand changes to the scope of practice registration standards. It includes tools like reflective practice guides and FAQs. Dental Board Scope Of Practice
- This article underscores the importance of reflective reports in managing professional indemnity claims. It provides guidance on how to document and analyze clinical incidents effectively. Professional Indemnity Insurance Claims For Dentists – Writing Reflective Reports
- The article reviews recent legal cases involving dentists, offering insights into common issues and outcomes. It serves as a learning tool for practitioners to avoid similar pitfalls. Professional Indemnity Insurance For Dentists – Recent Court And Tribunal cases
- This collection of articles provides legal tips on record keeping and managing complaints. It includes advice from Barry.Nilsson Lawyers on best practices and claim procedures. Doctor and Dentists Professional Indemnity Insurance Legal Articles
- The article outlines CPD requirements for dental practitioners and discusses the impact of COVID-19 on meeting these standards. It encourages ongoing education and compliance. Dentists Continuing Professional Development (CPD) and professional indemnity insurance
- This article addresses the importance of maintaining professional boundaries with patients. It provides scenarios and guidance to help practitioners avoid ethical and legal issues. Professional Indemnity Insurance For Dentists – Patient Boundaries
- The article explains the revised scope of practice standards and guidelines. It emphasizes the need for practitioners to understand their competencies and refer patients when necessary. DENTAL PRACTITIONERS, ARE YOU PRACTISING DENTISTRY WITHIN YOUR SCOPE OF PRACTICE ?
- This article discusses the obligations of dental practitioners to protect patient privacy. It includes a clinical scenario illustrating the consequences of a breach and offers safeguards to prevent such incidents. Professional Indemnity Insurance For Dentists : Patient Privacy
Financial Services Guide
Please click here for our Financial Services Guide, which includes important regulatory disclosures regarding our license, remuneration and complaints handling.
About Us Experien General Insurance Services Pty Ltd (ABN 77 151 269 279) AFSL 430190 – trading as Experien Insurance Services – arranges the Dental Professional Indemnity insurance and is not the insurer. For policies renewing from 1 May 2026 and new policies arranged from 1 May 2026, the insurance is arranged via Tego (ABN: 34 608 505 960 and AFSL: 482467) and insured with certain underwriters at Lloyd’s. Experien Insurance Services does not act as an agent of Tego or Lloyd’s. Historically, AAI Limited ABN 48 005 297 807 trading as Vero Insurance was the insurer for policies arranged by us and renewing up to 1 May 2019. Insurance Australia Limited ABN 11 000 016 722 AFSL 227681 trading as CGU Insurance was the insurer for policies arranged from 1 May 2019 to 30 April 2026. With effect from 1 October 2025, references in any documents to Insurance Australia Limited ABN 11 000 016 722 AFSL 227681 trading as CGU Insurance should be changed to CGU Australia Pty Ltd (CGUA) ABN 62 004 478 960 AFSL 700014 trading as CGU Insurance. In effecting the dental professional indemnity insurance contract with Vero or CGU, Experien General Insurance Services were acting under an authority given to it by the Insurer and Experien General Insurance Services effected the contract as agent of the Insurer and not the Insured. General advice on this website has been prepared without taking into account your objectives, financial situation or needs. Before acting on the advice, consider its appropriateness. Consider our disclosure documents, which include our FSG and the insurers’ Product Disclosure Statements (PDS)/ Policy Wording together with any policy schedules. Clients not satisfied with our services should contact our Complaints Officer. We expect that our procedures will provide a fair and prompt resolution to your complaint. If, however, you’re not satisfied with our final decision or if we haven’t been able to resolve the complaint to your satisfaction within 30 days, you may be able to take the complaint to the Australian Financial Complaints Authority (AFCA). AFCA provides fair and independent financial services complaint resolution that is free for consumers. AFCA has authority to review certain complaints. Contact them to confirm if they can assist you. You can contact the AFCA by 1800 931 678 (free call), info@afca.org.au or at www.afca.org.au.

